What waiting really costs, and what it buys
I’ve written about Social Security before.
Today, I’d like to share my thoughts on your Social Security decision and the trade-offs involved.
Let’s start with this image:
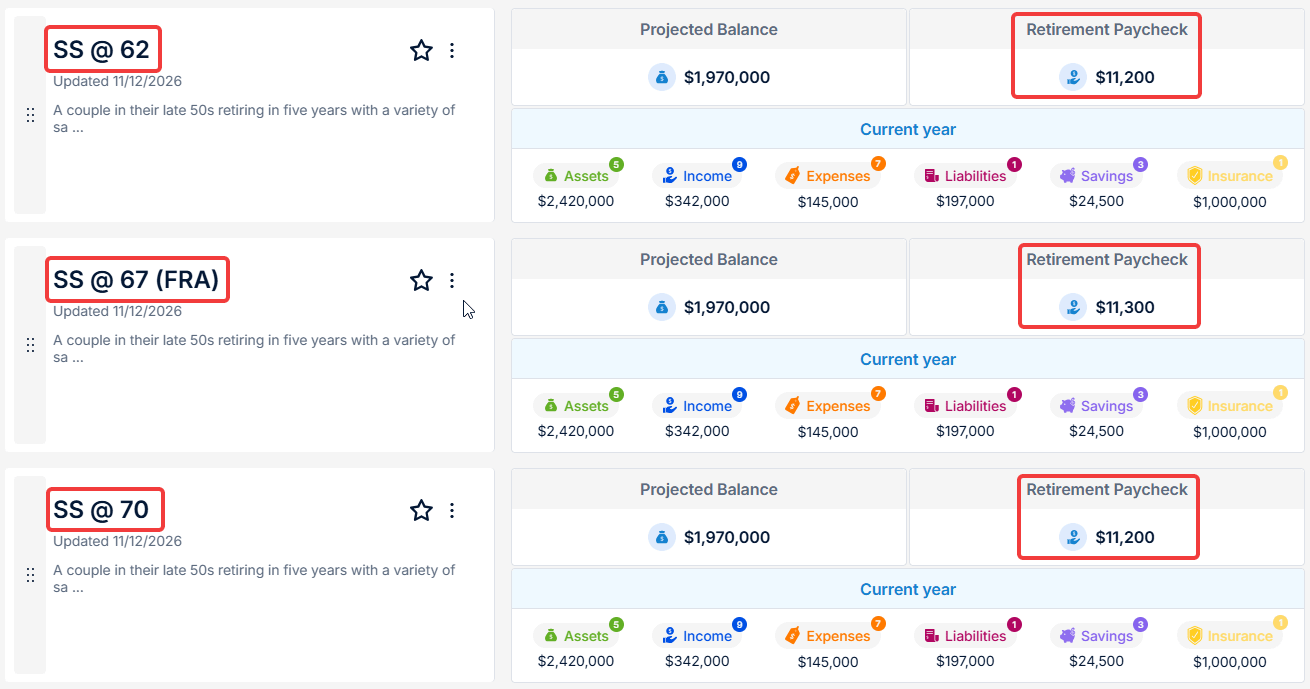
Above are 3 different planning scenarios for the same sample client couple. The only difference between the plans is when they start receiving Social Security.
As you can see, the impact on their retirement paycheck across the 3 plans is smaller than you might have guessed.
Of course, this reflects other details in their plan.
Today, we’re focusing just on Social Security.
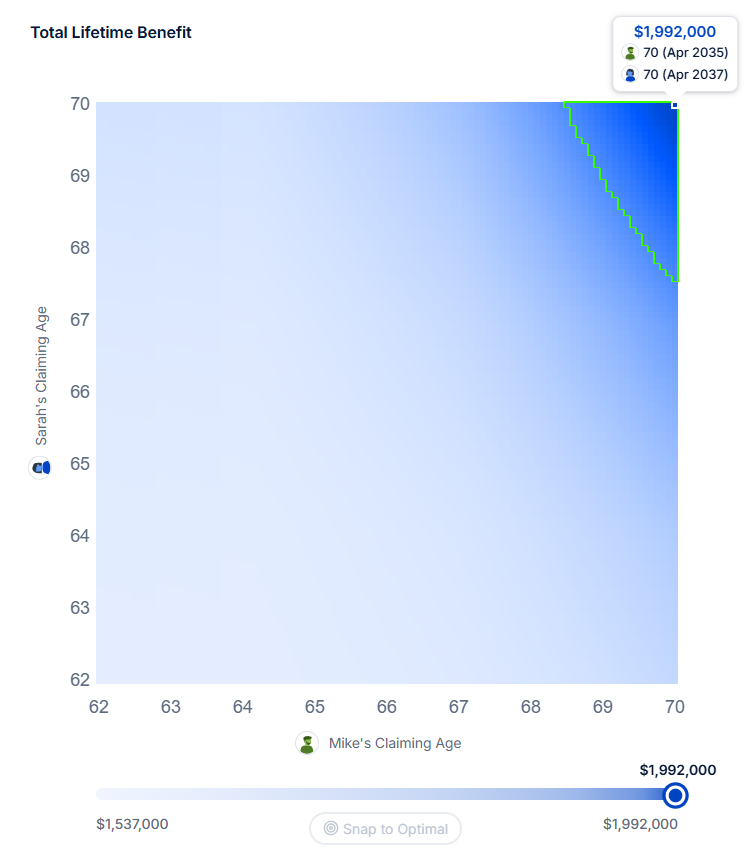
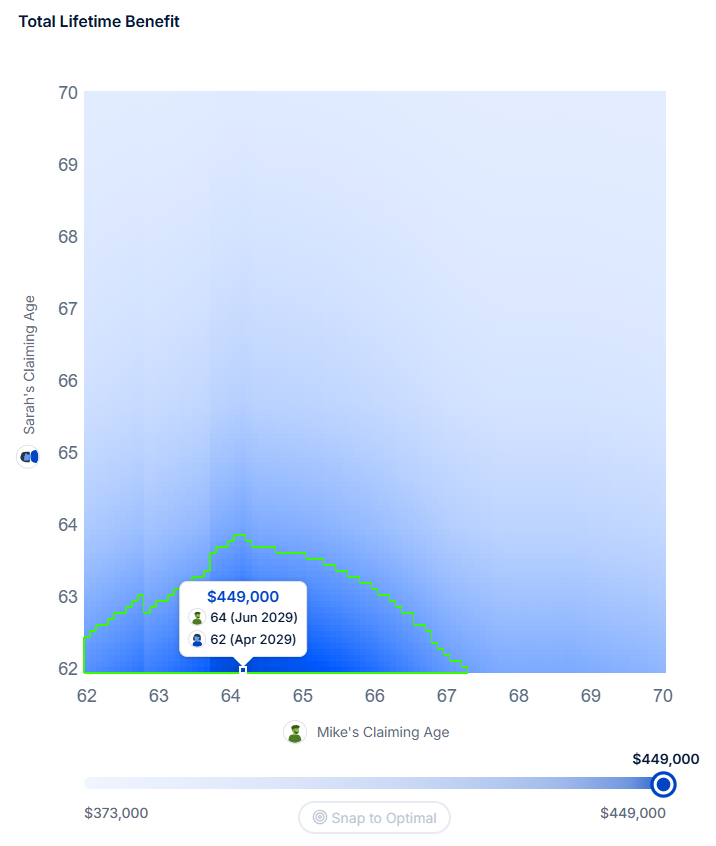
In the image above, you’ll see a chart with Mike’s claiming age on the horizontal axis and Sarah’s claiming age on the vertical axis.
If we simply wanted to solve for the their maximum Social Security dollar benefits, they both simply need to wait until age 70 to get almost $2 million in combined lifetime benefits.
If they both start Social Security at age 62, as you can see in the image below, they would receive a little over $1.5 million in combined lifetime benefits.
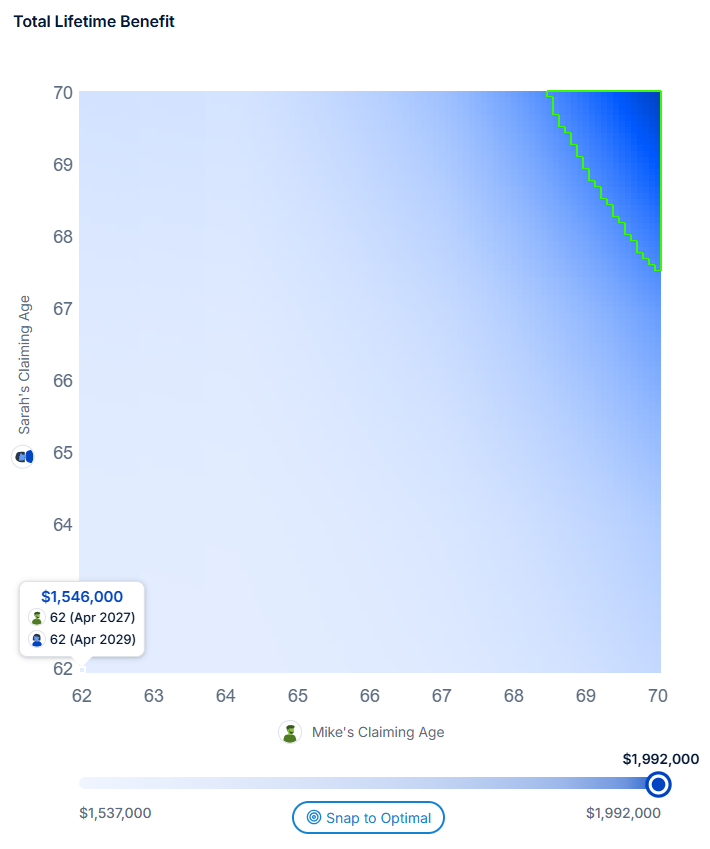
So how can a difference of almost $450,000 between age 62 and age 70 not have a bigger impact in their retirement paycheck in the first image above?
Because they would rely on their portfolio to “smooth” their spending and retirement paycheck over time, regardless of when Social Security benefits start.
But if we’re focusing on your Social Security decision, it’s all about trade-offs.
Life expectancy
For instance, for the age 70 start date to work, they have to live long enough to reach their “break even” ages:
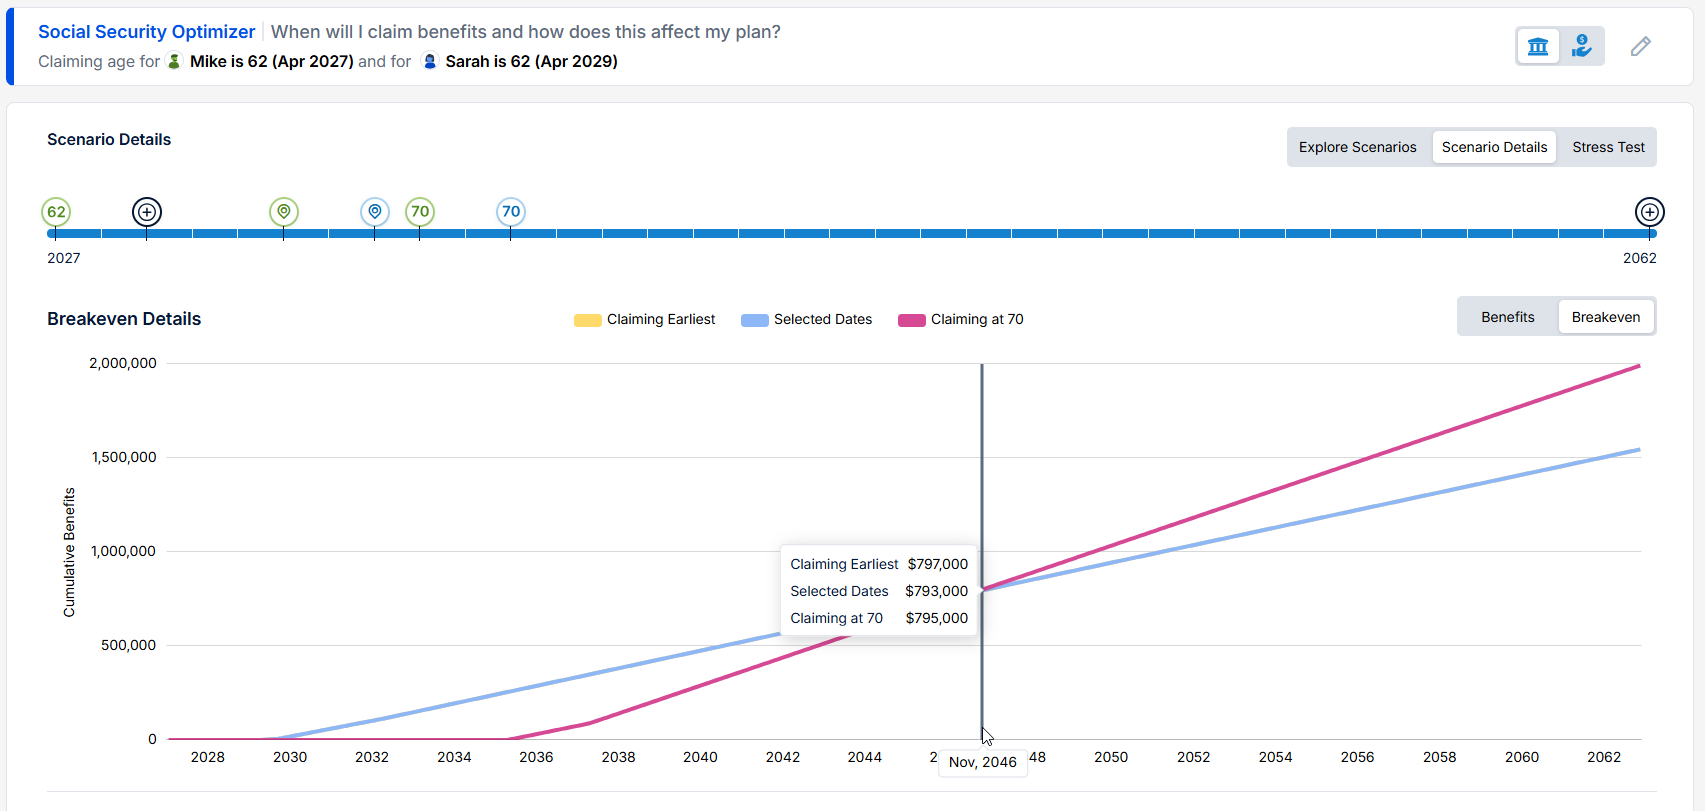
In the image above, we can see that Mike & Sarah need to both live at least another 20 years – until November, 2046 – for their age 70 start date to break even with if they’d both started at age 62.
And none of us know exactly how long we’ll live.
For example:
- If they each live to age 80, their ages to maximize Social Security are 67 for Mike and 64 for Sarah
- If they each live to age 75, Mike should start at age 64 and Sarah at age 62
The numbers above are only solving for their maximum combined lifetime benefits.
And that isn’t always the right goal to focus on.
Instead of “maximizing” your Social Security dollars, I would instead encourage you to “optimize” the role Social Security plays in your overall plan.
And your desired lifestyle.
Benefit reduction
Consider the potential impact of a Social Security benefit reduction in the future.
What if your benefits get cut by 23% starting in 2033? Some say this is likely.
Mike and Sarah should still wait until age 70 to maximize their benefits.
Opportunity cost
In last week’s essay, I mentioned opportunity cost.
This is another way to think about the necessary trade-offs that come with your money decisions.
But the opportunity costs rarely addressed in the Social Security decision involve what you’re potentially giving up while waiting for a larger benefit later.
A dollar in your hand today that you can use is worth more than a dollar in the future that may or may not be as valuable to you.
Consider your:
- Health and longevity – you might not be as healthy in the future and might not enjoy your money as much as you can today
- Missed investment growth – every dollar you get from Social Security today is one less dollar you need to use from your portfolio that could stay invested and compound over time
- Market risk – what if you need to use more of your portfolio during a period when the investment markets are down which can impact your long-term plan
- Peace of mind – research has shown that many people are more comfortable spending money from Social Security than from their portfolio
- Psychological and emotional return on investment – after paying into Social Security for 40+ years, waiting might be frustrating despite the math saying otherwise
For instance, more than once I’ve counseled clients to plan to wait until age 67 (their Social Security “full retirement age”) to start their benefits. But if the investment markets fall significantly, we can always start Social Security sooner rather than using their portfolio dollars at temporarily depressed values.
So what if, to account for the factors above, we apply a discount rate to your Social Security decision?
This discount rate would lower the value of future benefits to offset the “opportunity costs” (or trade-offs) in the list above.
For Mike and Sarah, a 5% discount rate doesn’t really impact their benefits maximization ages, suggesting they start at age 69 instead of age 70.
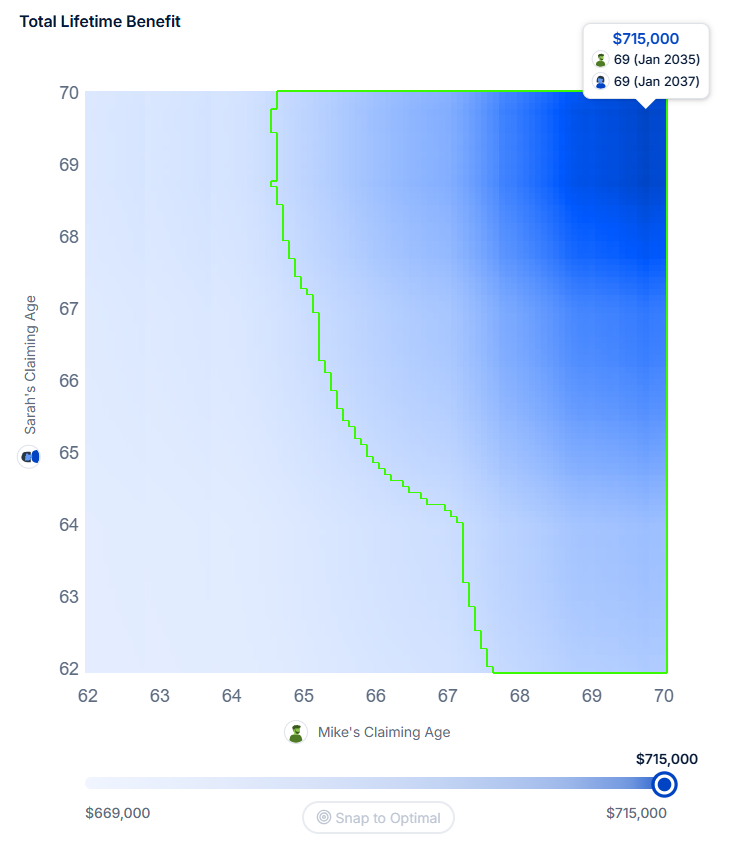
But what about the combined impact of all these factors together?
- For example, what if Mike lives to age 78 and Sarah survives him and lives to age 89?
- What if we also assume a benefit reduction of 23% starting in 2033?
- And what if we also add a 5% discount rate to reflect the potential opportunity costs?
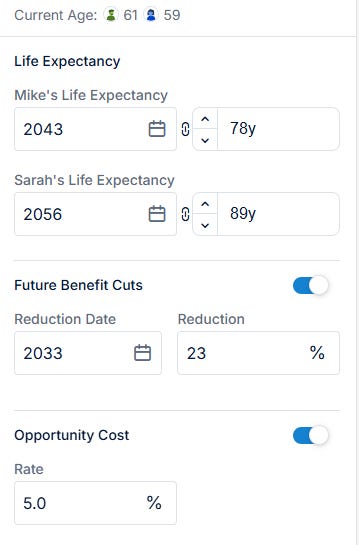
Based on the assumptions above, to maximize their combined lifetime benefits, Mike should start at age 64 and Sarah at age 62, as you can see below.
Now let’s see the impact your Social Security decision could have on your retirement paycheck if you were retiring in November, 2007, right before the 2008 global financial crisis.
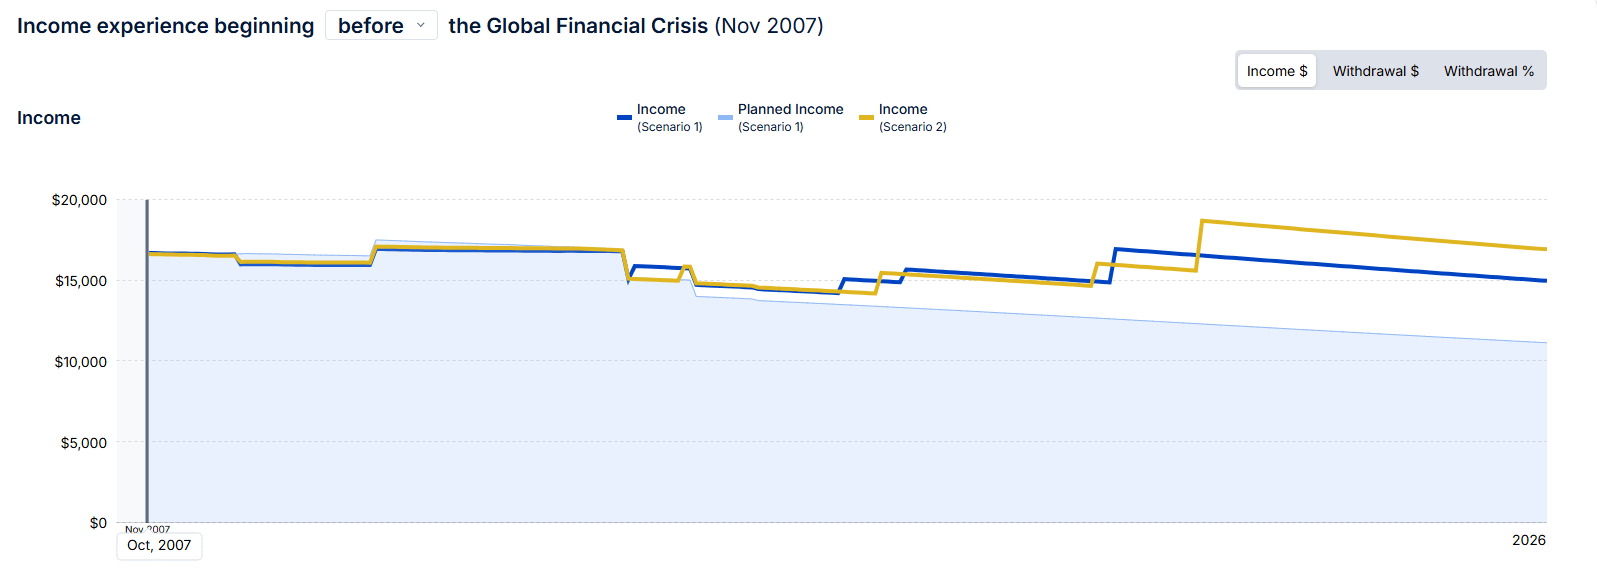
The image above shows that starting Social Security at age 62 (the yellow line) would have resulted in fewer and less severe reductions to your retirement paycheck throughout and beyond the 2008 global financial crisis.
And you would have ultimately had a meaningfully higher retirement paycheck from early 2022 until today.
And here’s the impact to your portfolio balance starting in November, 2007, with each of the Social Security start ages:
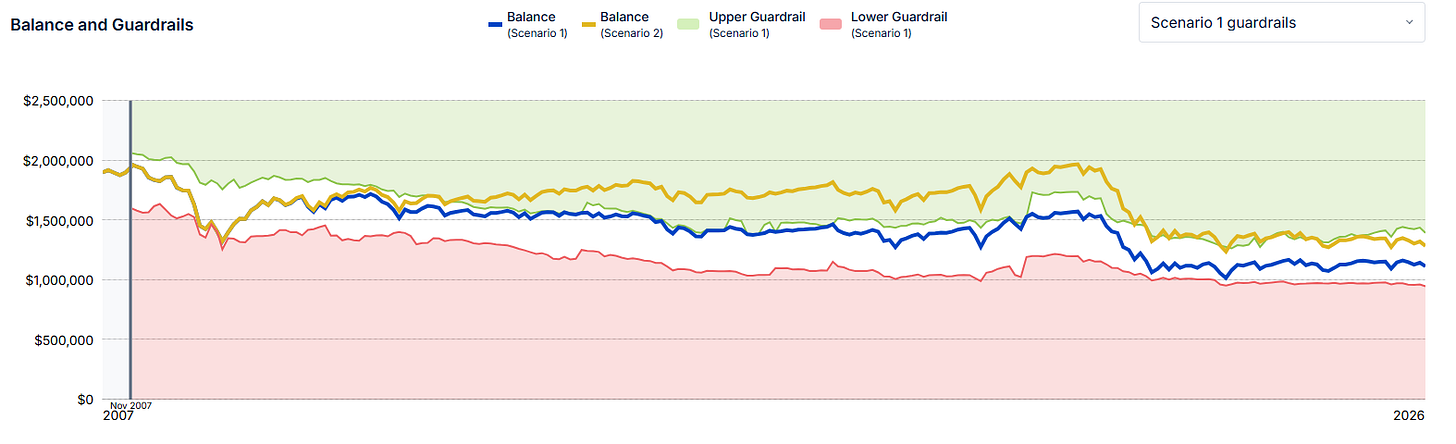
Waiting until age 70 would likely provide a much larger combined Social Security benefit over their lifetimes.
But Sarah and Mike would have maintained a larger portfolio balance (the yellow line) plus a larger retirement paycheck if they’d started their Social Security benefits at age 62.
At least based on the hypothetical analysis above.
Are you trying to maximize your Social Security benefit dollars or your retirement paycheck dollars?
Neither is right or wrong. It’s about what’s important to you.
It depends
My goal in writing this week’s essay isn’t to share the best way to make your Social Security decision.
There isn’t a best way.
There’s only your way.
The one that makes the most sense for you based on all the factors and assumptions above combined with the life you’re living today and want to continue living in the future.
Don’t forget the Tim Maurer quote,
“Personal finance is more personal than finance.”
I hope I’ve made the case that there are certainly trade-offs to consider when it comes to your Social Security decision.
I often encourage my clients to start their Social Security benefits sooner than later based on the simple fact that they can comfortably and confidently afford to do so.
This article appears on Russ’s weekly substack
Hypothetical Illustration: The examples and projections presented are hypothetical and provided for illustrative and educational purposes only. They do not represent actual client results or guaranteed outcomes. Calculations are based on assumptions regarding Social Security claiming ages, life expectancy, benefit adjustments, discount rates, investment returns, withdrawals, and historical market conditions. Changes in these assumptions may materially affect the results. Historical illustrations are presented with the benefit of hindsight and do not predict future results. Actual investment performance, portfolio balances, retirement income, and Social Security benefits will vary. Investing involves risk, including possible loss of principal.